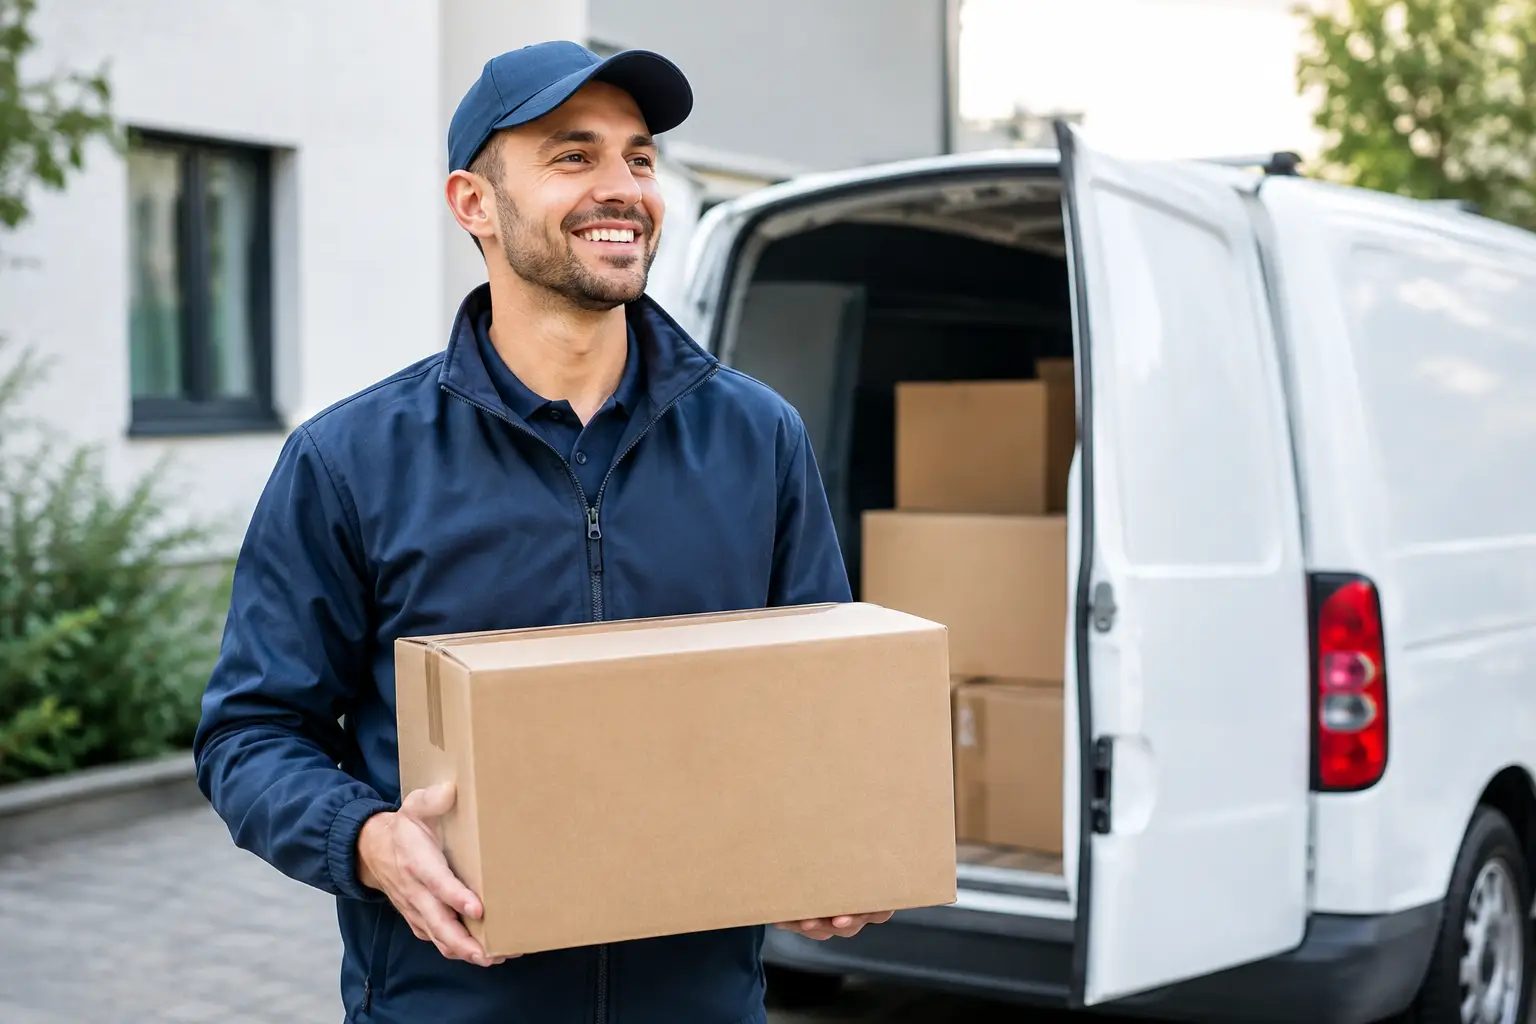
A delivery van can be your business’s most productive asset until an accident, theft or failed delivery stops it earning. Courier insurance is designed for drivers and businesses paid to carry other people’s goods, helping to protect vehicles used for hire and reward rather than ordinary business use.
For a single owner-driver, the right policy may be focused on one van and the types of parcels carried. For a growing operation with several drivers, different vehicle sizes and tight delivery schedules, fleet cover can make insurance easier to manage. The priority is the same: keep vehicles legal, protect the work you do and avoid unnecessary disruption when something goes wrong.
What is courier insurance?
Courier insurance is commercial motor insurance for vehicles used to collect, carry and deliver goods on behalf of customers or clients. It is commonly needed by parcel couriers, same-day delivery businesses, multi-drop operators, pharmacy delivery services and local firms carrying stock to customers.
The key distinction is hire and reward use. This means you are being paid to transport goods that belong to someone else. A standard social, domestic and pleasure policy, or even ordinary business-use cover, will not usually meet this requirement. Using the wrong class of use can leave a business exposed if it needs to make a claim.
The policy can be arranged for cars, vans and larger vehicles, depending on the work undertaken. Insurers will look closely at how each vehicle is used, where it operates, who drives it and the value and nature of the goods carried.
What courier insurance can include
The level of motor cover is usually chosen in the same way as other commercial vehicle insurance. Third party only meets the legal minimum for injury or damage to others. Third party, fire and theft adds protection if the insured vehicle is stolen or damaged by fire. Comprehensive cover can also cover accidental damage to the vehicle, subject to the policy terms and excess.
However, courier work brings additional risks that need separate consideration. The vehicle itself and the goods inside it are not automatically the same thing.
Goods in transit cover
Goods in transit insurance can protect the items you are carrying against insured events such as theft, loss or accidental damage. The right limit should reflect the maximum value likely to be in a vehicle at any one time, not simply the average parcel value.
A multi-drop van carrying a mixture of small parcels may need a different limit from a same-day courier moving high-value equipment. Policy conditions can also affect cover, including security requirements, unattended vehicle rules and whether particular goods are excluded. Checking these details before accepting specialist work is sensible.
Public liability and employer’s liability
Public liability insurance can help if a member of the public is injured or their property is damaged because of your business activities. For example, a delivery driver may accidentally damage a customer’s property while moving a bulky item.
If you employ staff, employer’s liability insurance is generally a legal requirement, subject to limited exemptions. It can cover compensation costs if an employee becomes ill or injured because of their work. These covers are separate from motor insurance but are often relevant to courier businesses trying to keep their protection organised in one place.
Optional operational cover
Depending on the insurer and policy, additional cover may be available for legal expenses, breakdown assistance, replacement vehicles or excess protection. These options should be judged against the cost of downtime and the alternatives your business has.
A replacement van may be particularly valuable for a business with fixed delivery commitments and no spare vehicle. It may be less necessary for an operator with vehicles available to redeploy. Cover is not automatically better because it is broader – it needs to suit how your operation would cope after a loss.
What insurers need to know about courier work
Accurate information is essential when arranging courier insurance. Courier activity covers a wide range of work, and insurers price it accordingly. A local bakery making short, regular deliveries presents a different risk from a driver completing national same-day jobs or a fleet working overnight in city centres.
Expect to provide details about your vehicles, drivers, claims history and the locations in which you operate. Insurers may also ask about annual mileage, delivery radius, overnight parking, security measures, the goods transported and whether work is subcontracted.
Be precise about the service you provide. Terms such as parcel delivery, own-goods carriage, haulage, removals and fast-food delivery are not interchangeable for insurance purposes. If your work changes during the policy period, tell your broker or insurer before assuming the existing cover still applies.
When fleet courier insurance may make sense
Fleet courier insurance can be a practical option when a business operates multiple vehicles, particularly if drivers and vans need to change regularly. Rather than administering separate policies with different renewal dates and documents, a fleet policy can place eligible vehicles under one arrangement.
This can reduce administration for an operations manager and give a clearer view of the cover in force across the business. It can also be useful where the fleet is mixed, such as a combination of small vans, Luton vans and cars used by supervisors.
The best arrangement depends on the number of vehicles, driver profile and insurer appetite. A small business with two vans may still benefit from fleet-style administration, while another may find individual policies more suitable. The value is not simply in combining policies – it is in having cover structured around how vehicles are actually used.
Managing the factors that affect cost
Premium is influenced by more than the value of the van. Claims frequency, driver age and experience, postcode, delivery area, overnight parking, annual mileage, vehicle security and the type of goods carried can all affect the price.
There are practical steps that may support safer, more consistent insurance arrangements. These include keeping driver records current, reporting incidents promptly, maintaining vehicles, using appropriate locks or tracking where needed and making sure drivers understand what to do after an accident or theft.
Avoid choosing a policy solely because it has the lowest premium. A lower price may come with a higher excess, restricted use, limited goods in transit cover or conditions that do not match your delivery model. Comparing the scope of cover alongside the cost gives a more useful picture.
Questions to ask before arranging cover
Before requesting a quote, establish whether you carry goods for payment, the highest value of goods likely to be in any vehicle, and whether any contracts specify minimum insurance limits. It is also worth checking whether customers require proof of public liability cover or particular goods in transit limits.
Ask how claims are handled outside normal office hours, whether windscreen and replacement-vehicle arrangements are available, and what security conditions apply when a vehicle is left unattended. If drivers use their own vehicles, clarify whether they need their own hire and reward insurance rather than relying on your business policy.
For fleets, ask how vehicles and drivers are added or removed, whether any-driver cover is available and what information is needed for mid-term changes. These are the details that affect day-to-day administration long after the policy has been arranged.
Get the cover aligned with the deliveries you make
Courier work moves quickly, but insurance decisions should not be rushed. A clear description of your delivery service, vehicles, drivers and goods gives an adviser the best chance of identifying suitable options from the outset.
Fleet Brokers can help delivery businesses consider fleet motor, goods in transit and related business insurance requirements with straightforward, UK-based support. Speak to a specialist before your next job changes the risk your policy was built to cover.