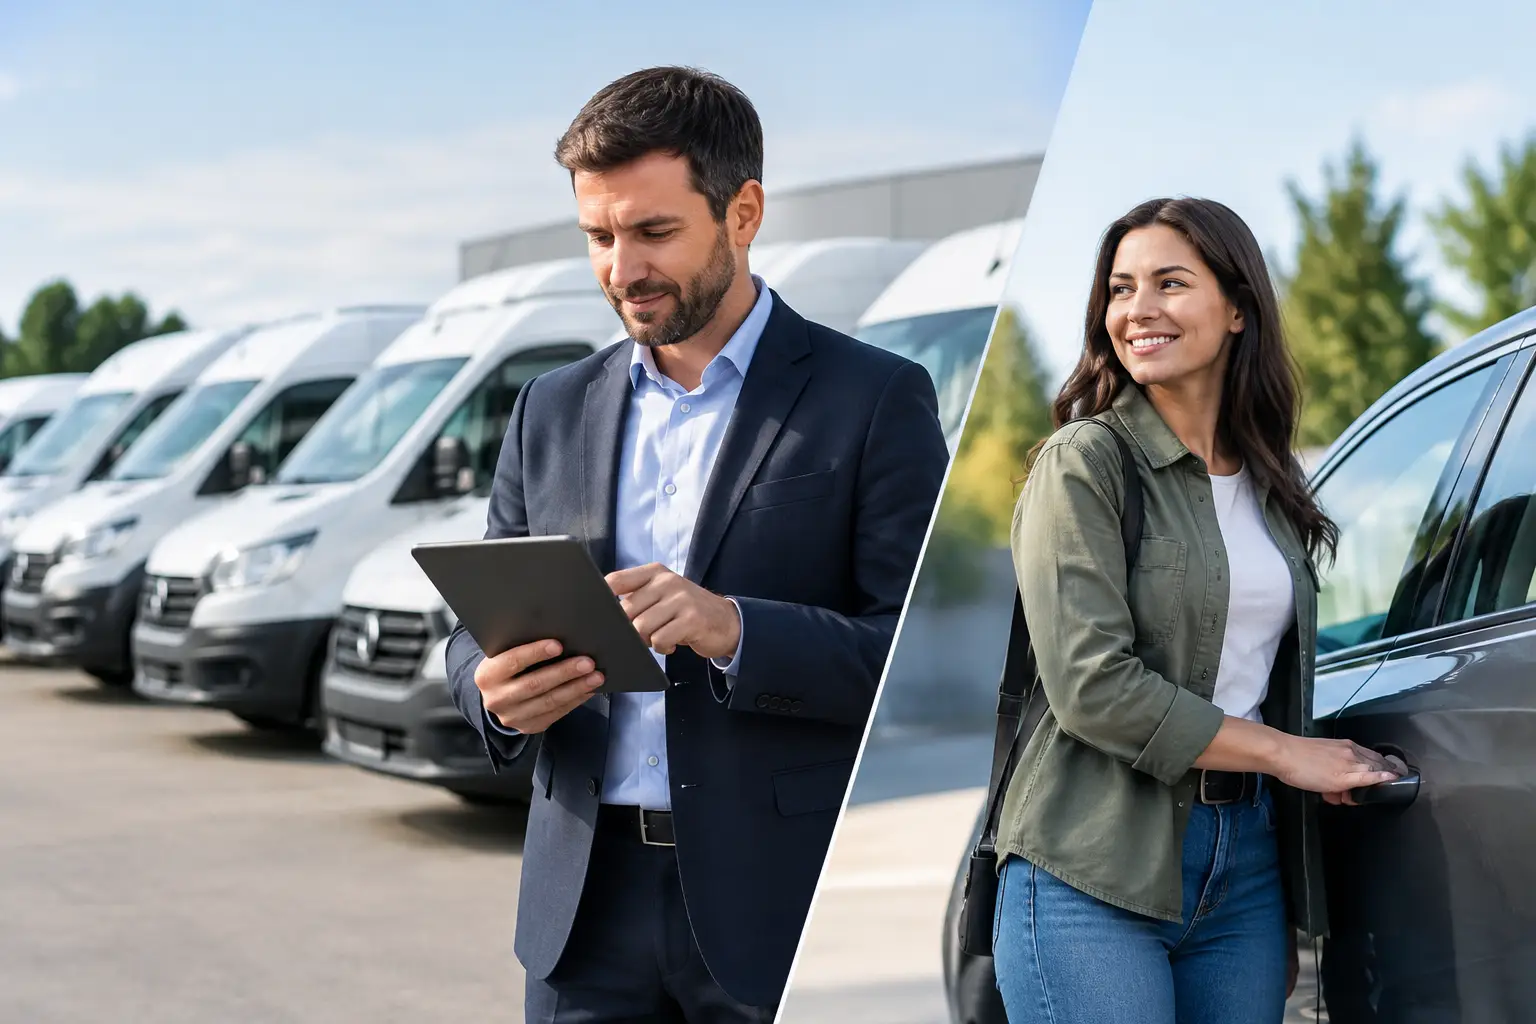
A missed renewal date can leave a van off the road just when it is needed most. For businesses running several vehicles, the choice between a fleet policy versus individual policies is not only about the premium. It affects administration, driver management, claims handling and how easily the business can adapt when vehicles are bought, sold or reassigned.
A fleet policy brings eligible vehicles together under one commercial insurance arrangement. Individual policies insure each vehicle separately, often with different renewal dates, insurers and policy terms. Neither approach is automatically right for every business, but the practical differences become more significant as your operation grows or becomes more varied.
What is a fleet insurance policy?
Fleet insurance is designed for organisations operating multiple vehicles. Depending on insurer criteria and the nature of the business, it can cover cars, vans, lorries, minibuses, agricultural vehicles, plant, trailers and specialist vehicles under one policy.
Rather than managing separate certificates, renewals and insurer contacts for each vehicle, you have one policy period and one central set of documents. Cover can usually be arranged around the way vehicles are actually used, whether that means local trade work, courier deliveries, long-haul transport, carrying passengers or travelling between client sites.
The minimum number of vehicles accepted varies between insurers. Some fleet arrangements may suit a small business with two or three vehicles, while others are intended for larger operations. The vehicle types, claims history, driver ages, business activity and postcode areas will all affect the options available.
Fleet policy versus individual policies: the operational difference
With individual policies, each vehicle is separately insured. This can work well for a very small business with stable vehicle ownership, especially where one vehicle has specialist requirements that do not fit comfortably with the others. It may also make sense where a director’s vehicle and a business van need distinctly different cover.
The trade-off is administration. Each policy can have its own insurer, excess, renewal date, no-claims position and mid-term adjustment process. If you operate five vans purchased at different times, you could be dealing with five renewal reminders and five sets of documents each year.
A fleet policy creates a more joined-up approach. Adding a replacement van, removing a written-off vehicle or updating driver details can be handled through one policy, subject to insurer agreement and any additional premium. For a transport manager or administrator, that can mean fewer moving parts and a clearer view of what is insured.
It does not mean every vehicle receives identical cover. A well-arranged fleet policy can reflect different uses within the same business. For example, a construction company may need cover for site vans, company cars and a pickup towing a trailer. A courier operation may need hire-and-reward use for its delivery vehicles, while office-based cars are covered for business travel.
Where a fleet policy can save time and improve control
The strongest case for fleet cover is often operational rather than purely financial. One renewal date helps businesses review their entire vehicle risk at the same time. That creates an opportunity to check vehicle values, driver restrictions, mileage, overnight parking arrangements and changes in how the fleet is used.
It can also make compliance easier to manage. A central policy record helps you confirm that a new vehicle has been declared and that the use class matches the work being carried out. This matters where a vehicle’s role changes quickly, such as a van moving from general trade work into timed deliveries or a car becoming part of a field-service team.
Claims are another consideration. Separate policies can mean contacting different insurers after incidents involving different vehicles. With fleet cover, there is normally one policy reference and a single route for notifying incidents. That does not alter the need to report facts promptly, preserve evidence or follow the insurer’s claims process, but it can reduce uncertainty at a stressful time.
For businesses with a mixed fleet, consolidation may also improve visibility over total insurance spend. It is easier to budget when vehicles renew together, although the final premium will still depend on the risk profile and the insurer’s underwriting assessment.
When individual vehicle policies may still be suitable
A fleet policy is not always the most suitable or lowest-cost option. If you run only two vehicles with very different uses, buying separately can sometimes provide more tailored cover. For instance, a heavily modified specialist vehicle or a high-value executive car may be better placed on a dedicated policy, depending on insurer appetite.
Individual policies can also be worth comparing when there is a difficult claims history attached to one vehicle or driver. Separating that risk may, in some circumstances, prevent it from influencing terms for the rest of the fleet. Equally, some insurers prefer to see all business vehicles together, so this should be considered case by case rather than assumed.
The key question is whether separate arrangements genuinely give you better protection and value once the additional administration is considered. A cheaper price for one van can lose its appeal if it creates a gap in use, a forgotten renewal or unnecessary time chasing paperwork.
Cover details matter more than the policy structure
Whether you choose a fleet policy or individual policies, the schedule and wording need to match your day-to-day work. Third-party only, third-party fire and theft, and comprehensive cover offer different levels of protection. Comprehensive cover does not automatically include every risk a business may face.
You may need to consider areas such as business use, carriage of own goods, hire and reward, tools in transit, trailer cover, windscreen cover, breakdown assistance, replacement vehicle provision and European use. Goods in transit, public liability and employer’s liability are separate covers that may also be relevant, particularly for delivery, construction, removals and service businesses.
Driver arrangements deserve close attention. Some fleets benefit from named drivers, while others need any-driver cover or a defined age limit to keep vehicles available across shifts. More flexible driver cover can be useful, but it may affect price and insurer terms. Always disclose convictions, claims, vehicle modifications and changes in business activity accurately.
A practical way to compare your options
Before requesting quotes, gather an up-to-date vehicle list with registrations, values, uses, annual mileage and where each vehicle is kept overnight. Record who drives each vehicle, including their age, licence details and claims or conviction history. This gives insurers a clearer picture and helps avoid time-consuming changes later.
Then look beyond the headline premium. Compare excesses, permitted vehicle use, driver restrictions, payment options, replacement vehicle terms and claims support. Ask how additions and removals are handled during the policy year, particularly if your business regularly hires vehicles, replaces vans or takes on seasonal staff.
A specialist broker can help present a mixed or unusual fleet clearly to suitable insurers. Fleet Brokers, operating through Quote Me Today, can compare fleet options through a broad panel and explain the terms in plain English, helping you make a decision based on the realities of your operation rather than a headline price alone.
Choose the arrangement that keeps work moving
The right policy structure should support the way your business operates now, while leaving room for reasonable change. A stable two-vehicle firm may be well served by individual cover. A growing business with several vans, cars or specialist vehicles will often benefit from the control of a single fleet policy.
Before renewal, take stock of every vehicle, every driver and every use case. A short review now can prevent the more costly disruption of discovering that a vehicle, journey or driver was not insured as expected when the business needs to keep moving.