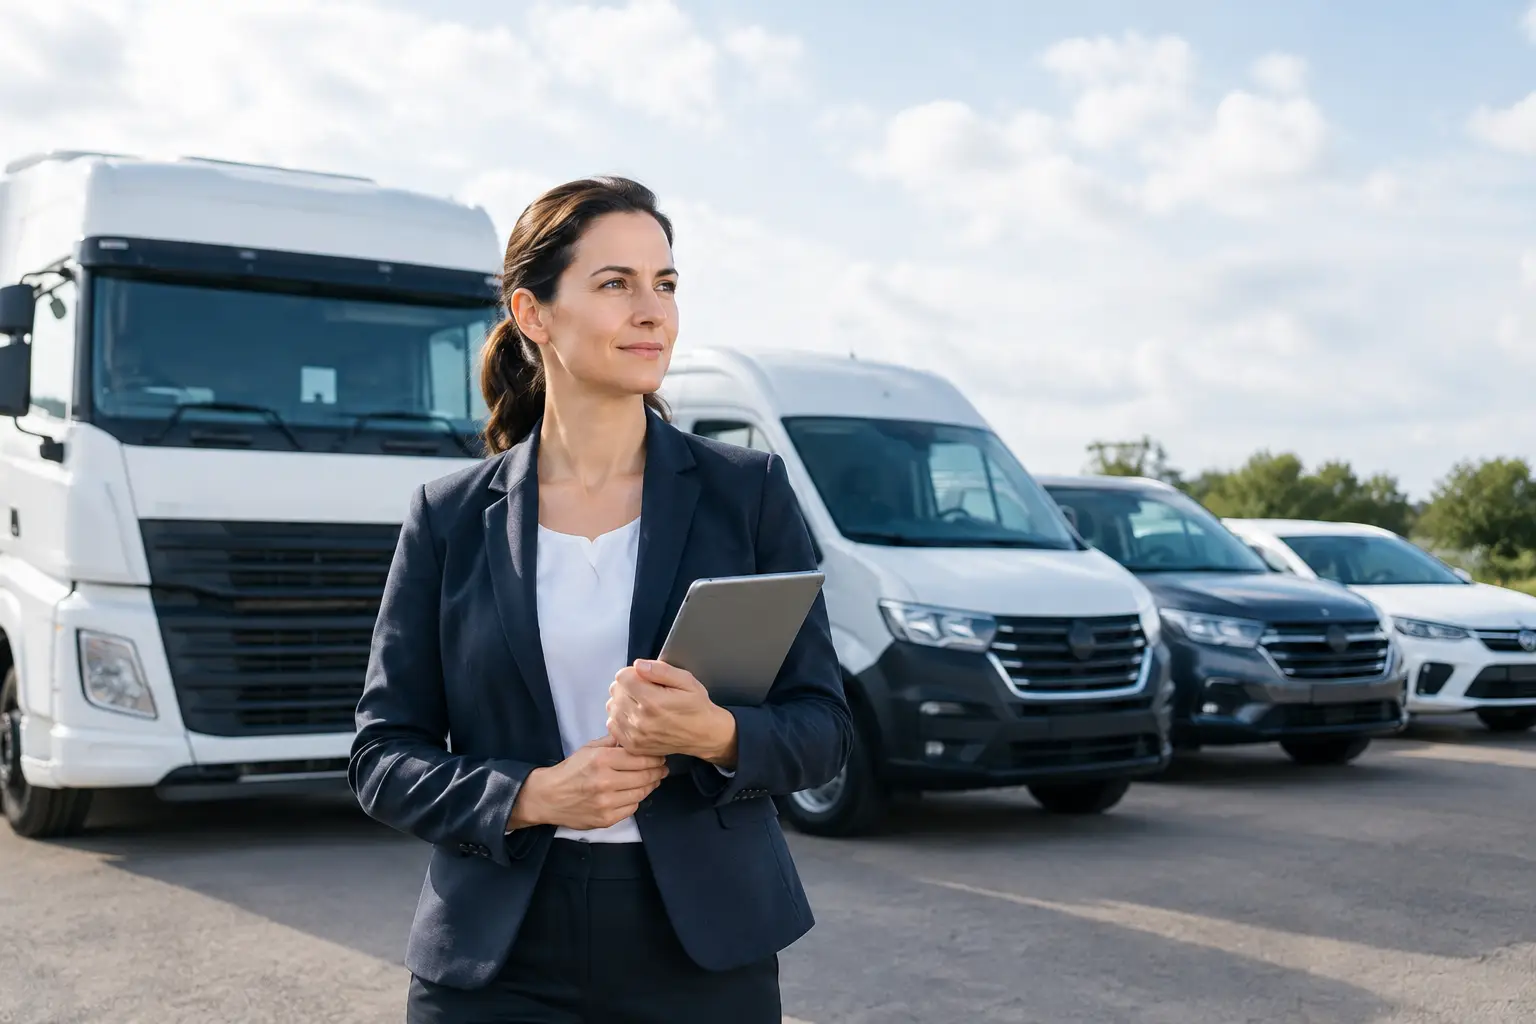
A business rarely grows with one neat row of identical vehicles. A plumbing firm may run vans and a director’s car. A construction company might have pickups, tippers, plant and trailers. A rural contractor may need cover for 4x4s, agricultural machinery and forestry vehicles. Mixed fleet insurance is designed for these real-world operations, giving eligible vehicles a home under one commercial policy rather than leaving you to manage several separate renewals.
The attraction is straightforward: less administration, a clearer view of your cover and one point of contact when something goes wrong. But a mixed fleet policy is not simply a collection of vehicles on a spreadsheet. Insurers will look closely at how every vehicle is used, who drives it and the risks created by the combination. Getting those details right is what helps a policy support the business when vehicles need to stay on the road.
What is mixed fleet insurance?
Mixed fleet insurance is a commercial motor policy that can cover different vehicle types within one arrangement. Depending on the insurer and the nature of your business, it may include company cars, vans, pickups, minibuses, lorries, courier vehicles, trailers, plant and specialist vehicles.
Rather than renewing a van policy in March, a car policy in June and a lorry policy in October, you have one policy period and one set of core documents. Vehicles can usually be added or removed during the term, subject to insurer agreement and any additional premium or return premium that applies.
This does not mean every vehicle receives identical cover. A policy may apply different excesses, driver restrictions, usage terms or sections of cover to particular vehicle groups. For example, a company car used for sales visits may be rated differently from a van carrying tools, while a lorry used for regional haulage will need terms that reflect its weight, routes and load-related exposure.
When a mixed fleet policy may suit your business
Mixed fleet cover is often worth considering when vehicle variety is creating unnecessary admin. It can suit a business with a modest number of vehicles as well as a larger operation, although minimum vehicle numbers and acceptable mixes vary between insurers.
It is particularly relevant where vehicles share a common business purpose but perform different jobs. A facilities management business may have engineers in vans, supervisors in cars and a minibus for larger teams. A removals company could operate Luton vans, larger lorries and support vehicles. A charity may need cars for staff visits alongside accessible minibuses.
The key question is not simply how many vehicles you own. It is whether one policy can reflect how the fleet is managed. If separate policies give you more suitable terms for a specialist vehicle, keeping that vehicle outside the fleet arrangement can sometimes be the sensible option. The best structure depends on the fleet, the insurer’s appetite and the cover required.
Which vehicles can be included?
A mixed fleet can be broad, but eligibility is always subject to underwriting. Insurers commonly consider combinations such as:
- Cars, electric vehicles, vans and pickups
- HGVs, tippers, rigid lorries and articulated vehicles
- Courier, delivery and hire-and-reward vehicles
- Minibuses and other passenger-carrying vehicles
- Agricultural machinery, forestry vehicles, plant and trailers
Specialist vehicles need particular care. A trailer may require its own declaration even where it is attached to an insured vehicle. Plant may need cover while being transported, while working on site or both. Passenger transport, courier work and hire and reward can involve additional insurer requirements because the vehicle use carries a different level of risk.
Give your broker a full vehicle schedule, including registrations, values, carrying capacities and any modifications. It is also useful to explain whether vehicles are owned, leased, hired in or occasionally borrowed. Leaving a vehicle type out of the original discussion can delay a quote or create a gap in expectations about what the policy covers.
What cover should you consider?
The legal minimum for vehicles used on UK roads is third-party cover, but many businesses choose broader protection. Comprehensive cover can include accidental damage to your own vehicles, while third-party fire and theft offers a middle ground. The right choice comes down to vehicle values, cash flow, downtime exposure and your ability to absorb an uninsured loss.
A mixed fleet policy can also be tailored with extensions, where available. These may include windscreen cover, replacement vehicle provision, legal expenses, breakdown assistance or cover for personal belongings. The precise wording, limits and exclusions matter. A replacement vehicle, for instance, may only be available following a covered loss, for a limited period and in a specified vehicle class.
Businesses carrying customers’ property should also consider goods in transit insurance. Motor cover protects the vehicle and its road-use liability; it does not automatically insure the goods being carried. Likewise, employers’ liability, public liability and commercial property insurance address different risks and should not be assumed to sit within a fleet policy.
The details insurers need to price the risk
A fast, accurate quotation starts with a clear picture of the operation. Insurers will usually ask for vehicle details, driver information, claims history and intended use. They also need to understand where vehicles travel, where they are kept overnight and what security arrangements are in place.
Usage descriptions deserve more than a tick-box answer. “Business use” could mean local engineering visits, nationwide deliveries, site-to-site construction work or carrying fare-paying passengers. These are materially different risks. Be clear about annual mileage, overnight parking, goods carried, cross-border travel and whether drivers take vehicles home.
Driver management has a direct bearing on terms. State the age range of drivers, their licences, convictions, endorsements and previous claims accurately. If drivers are permitted to use any vehicle, a policy may be arranged on an any-driver basis where appropriate, but this can cost more than named-driver arrangements. Restricting access can help control premium, though it may be less practical when shifts, sickness or urgent jobs require flexibility.
Claims performance also tells an insurer how the fleet is controlled. Keep records of incidents, even where you did not make a claim, and explain improvements made after losses. Dash cameras, driver training, vehicle checks, secure parking and clear reporting procedures may all be relevant, but they do not guarantee lower premiums. Each insurer assesses them alongside the overall risk.
Managing additions, removals and changes
A fleet changes quickly. A new contract may require three extra vans next week, or a damaged vehicle may be replaced at short notice. Tell your broker before a new vehicle is used wherever possible. Cover is not automatic simply because another vehicle is already listed on the policy.
The same principle applies to changes in use. A van that moves from carrying your own tools to making paid deliveries, or a minibus that starts transporting passengers for reward, may no longer match the original declaration. Promptly reporting changes gives the insurer the opportunity to confirm cover and adjust terms if necessary.
Keep a simple internal process: one person should maintain the vehicle schedule, record driver changes and notify the broker. This reduces the risk of duplicated records, uninsured assumptions and avoidable mid-term confusion. It also makes renewal far less disruptive.
Balancing price, protection and downtime
The cheapest premium is not always the lowest-cost choice for an operational fleet. A higher excess can reduce the premium but may be painful if several smaller incidents occur. Comprehensive cover may cost more than third party cover, but a write-off could be far more expensive if the vehicle cannot be replaced quickly.
Ask practical questions while comparing options. Are courtesy or replacement vehicles available? Is there a restriction on drivers, mileage or territories? What happens if a vehicle is off the road after an accident? How are claims reported outside normal office hours? The answers can matter as much as the headline price when staff, jobs and customers depend on the fleet.
An independent broker can compare insurer options and explain the trade-offs in plain English. Fleet Brokers can help businesses present mixed vehicle risks clearly, arrange suitable fleet cover and provide a central contact for policy changes and claims notification. Cover is always subject to insurer acceptance, policy terms, conditions, limits and exclusions.
A practical way to prepare for a quote
Before speaking to a specialist, gather your current policy schedule, renewal date, claims record and a complete vehicle list. Include how each vehicle is used, who can drive it and any specialist equipment or trailers involved. If your fleet has changed since the last renewal, say so early rather than relying on old information.
This preparation does more than speed up the process. It helps ensure that a policy built around cars, vans, lorries or specialist machinery reflects the way your team actually works. The right mixed fleet arrangement should make administration simpler without treating operational detail as an afterthought – so when the next vehicle changes, you know exactly who to call and what needs to be checked.