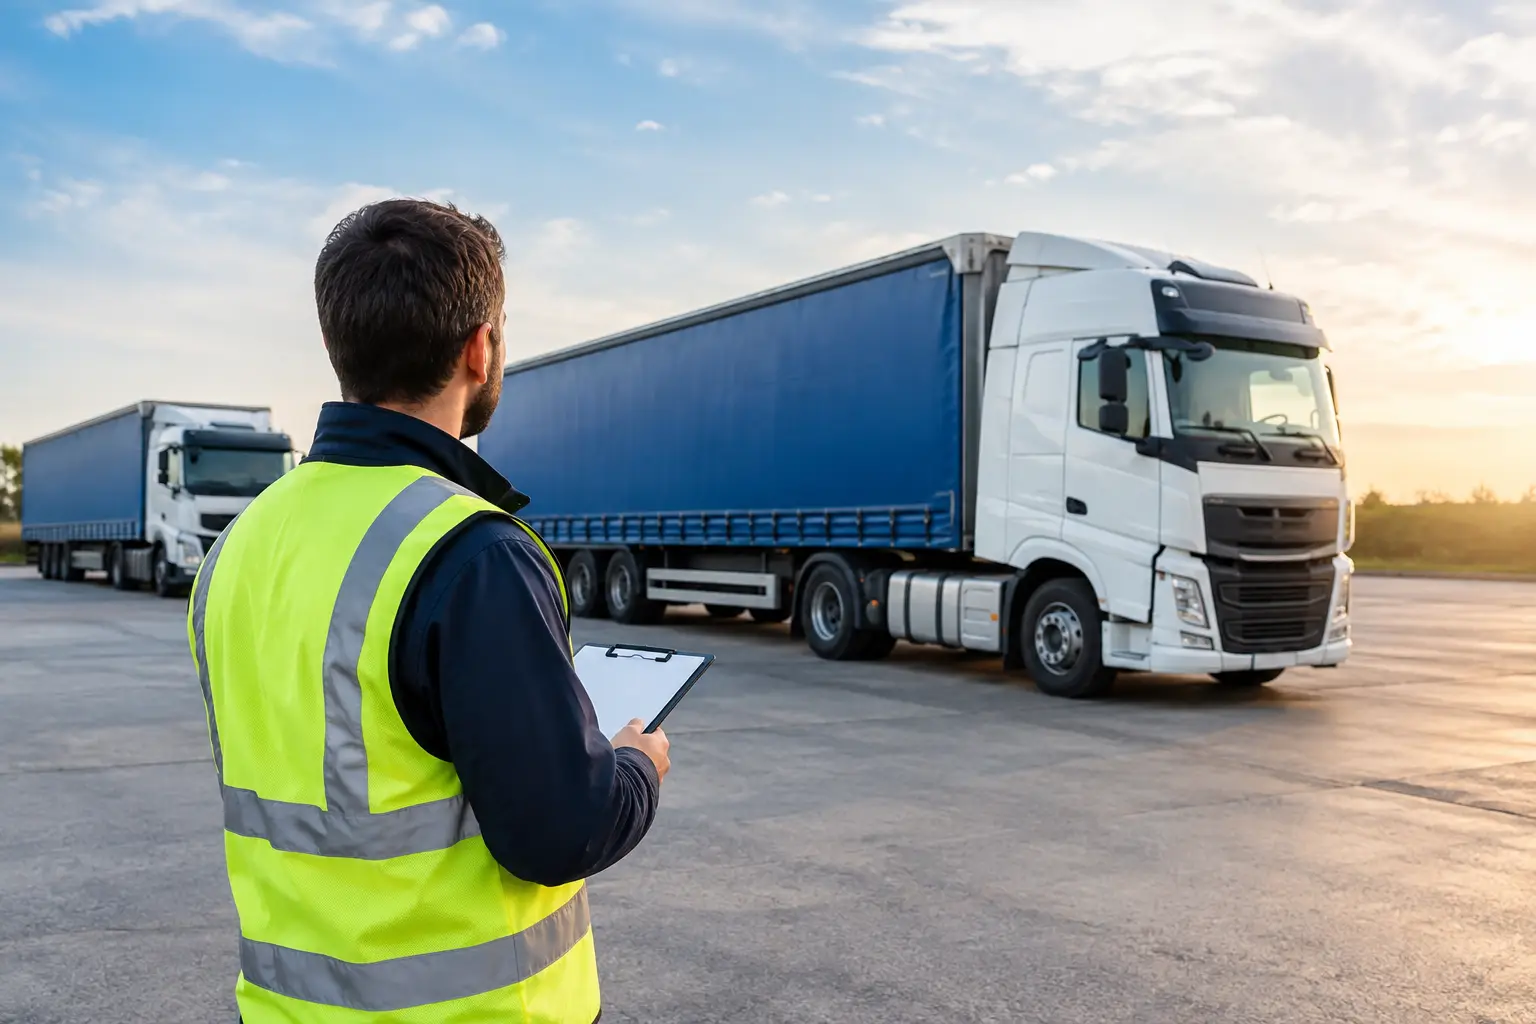
A trailer can be a small part of a fleet on paper, but a large part of the day’s work. Whether it carries tools to site, plant between contracts, livestock equipment or materials for a customer delivery, an uninsured or incorrectly declared trailer can create costly disruption. Trailer fleet insurance UK arrangements can help businesses place trailers alongside the vehicles that tow them, with clearer administration and cover suited to how the fleet operates.
For businesses running several vehicles, trailers and drivers, the aim is not simply to find the lowest premium. It is to make sure the policy reflects the equipment in use, where it travels, who tows it and what happens when there is a loss. That makes renewal, claims handling and day-to-day fleet management more straightforward.
What is trailer fleet insurance?
Trailer fleet insurance usually refers to cover for trailers arranged within a wider commercial fleet policy. Rather than treating every trailer as an afterthought, the business can declare its trailer stock as part of the insured fleet, subject to the insurer’s acceptance criteria and policy terms.
A fleet policy may include cars, vans, lorries, agricultural vehicles, plant and trailers under one policy schedule. This can be particularly useful where trailers move between tow vehicles or are used by different employees. One renewal date and one set of policy documents can reduce the administration involved in keeping cover up to date.
The exact approach varies. Some insurers require individual trailers to be listed, especially higher-value plant trailers or specialist units. Others may offer a more flexible basis for a defined number or class of trailers. The right option depends on the trailer values, their use, security arrangements and the wider fleet claims history.
Does motor fleet insurance automatically cover a trailer?
Not always. A towing vehicle’s policy may provide some cover for third-party liabilities while a trailer is attached, but this does not necessarily mean the trailer itself is insured for accidental damage, theft, fire or damage while detached. It also may not meet the needs of a business that owns several trailers or uses specialist equipment.
This distinction matters when a trailer is parked at a depot, left on a customer site or stolen overnight. The trailer may have significant value in its own right, while its contents could require separate goods in transit, tools or plant cover. Relying on assumptions can leave gaps at the point a business needs to make a claim.
A specialist adviser will ask how each trailer is used and stored before recommending an arrangement. Clear answers at quotation stage are valuable: insurers need an accurate picture to assess the risk and to avoid problems later.
What can a trailer fleet policy cover?
Cover depends on the insurer and the level selected, so policy documents should always be checked carefully. A comprehensive fleet policy can often be tailored to include the following areas:
- accidental damage to insured trailers, including damage sustained while in use;
- theft of a trailer, subject to agreed security requirements and policy conditions;
- fire damage and third-party liability arising from trailer use;
- replacement or repair costs, based on the sums insured and settlement terms; and
- cover for trailers while attached to an insured towing vehicle, and in some cases while detached.
Third-party only cover is generally the minimum level required for road use, but it will not normally pay to repair or replace the business’s own trailer after a fire, theft or accident. Comprehensive cover may cost more, yet can be more appropriate for newer, specialist or high-value equipment. For older utility trailers with limited replacement cost, a business may take a different view. It depends on the financial impact the loss would have on operations.
Trailers that businesses commonly insure
Commercial fleets use trailers in many forms. A construction company may need plant trailers and flatbeds; a landscaping business may operate tipping trailers and machinery carriers; a haulage operator may use drawbar units; and a farming or forestry business may need trailers designed for agricultural work.
Other common examples include box trailers, car transporters, refrigerated trailers, catering trailers, horseboxes used in connection with a business, welfare units and generator trailers. Specialist trailers can bring additional underwriting questions because of their size, value, load, usage or security needs.
If a trailer is modified, hired out, used for hazardous loads or taken outside the UK, say so at the outset. These factors may affect the insurer’s terms. A policy should also reflect whether drivers tow trailers occasionally or as a routine part of their role.
The details insurers will want to know
Good fleet insurance starts with a clear risk presentation. Insurers commonly consider the number and type of trailers, their values, where they are kept overnight, the tow vehicles involved and the nature of the business. They will also look at driver experience, claims history, operating radius and any risk-management controls already in place.
Security is often a key issue. Wheel clamps, hitch locks, tracking devices, gated compounds and secure storage can all be relevant, particularly for high-value trailers. However, a security measure only helps if it is used consistently and meets any policy requirement. If an insurer makes a lock or tracker a condition of cover, the business needs a practical process for checking compliance.
It is equally useful to keep an up-to-date trailer register. Record the make, model, serial or chassis number, value, location, security fitted and any significant modifications. This supports a more accurate quotation and can make a theft claim easier to evidence.
Managing mixed fleets on one policy
A single fleet policy can make particular sense for businesses that run a mixture of vans, cars, lorries and trailers. Drivers may move between vehicles, trailers may be allocated at short notice, and the person managing insurance may have many other operational responsibilities. Consolidating the cover can reduce duplicated paperwork and make changes easier to manage.
That said, combining everything is not automatically the best route. A business with unusual trailer use, very high-value assets or a poor claims record may benefit from a separate specialist arrangement for part of its risk. The important point is that the policy structure matches the business, rather than forcing the business into a standard package.
Fleet Brokers can assess mixed vehicle and trailer risks through a broad insurer and wholesale broker panel, explaining the available options in plain English. As an FCA-regulated broker, the focus is on arranging suitable cover based on the information provided, not making assumptions about what a standard motor policy may include.
How to reduce trailer claims and downtime
Insurance responds after an insured incident. Practical controls can reduce the chance of a claim and help keep the fleet moving when one occurs. Regular trailer inspections are essential: tyres, lights, brakes, coupling mechanisms, breakaway cables and load restraints should be checked before use and maintained in line with legal and manufacturer requirements.
Drivers should be authorised and trained to tow the equipment they use. This includes understanding towing weights, safe loading, reversing, securing loads and the checks needed before departure. A minor reversing incident or improperly secured load can quickly become a costly claim, particularly around sites, depots and public roads.
When a loss does happen, report it promptly and keep photographs, police crime references where applicable, repair estimates and any third-party details. Fast notification gives insurers and claims teams the best opportunity to assess the situation, arrange repairs or recovery, and limit avoidable delay.
Choosing cover that works when the trailer is needed
Before accepting a quotation, ask practical questions. Is the trailer covered when detached? Are all towing vehicles and authorised drivers included? Is theft cover subject to a specific lock, tracker or storage condition? Does the sum insured represent today’s replacement cost? Are tools, plant or goods carried in or on the trailer insured elsewhere?
These are not technicalities. They are the details that determine whether cover responds as expected after a theft from a yard, a collision on the motorway or damage while moving equipment between jobs.
A trailer should not be the overlooked asset in an otherwise well-managed fleet. Taking time to describe its use accurately and review the terms before cover begins gives your business a stronger basis for keeping jobs, deliveries and services on schedule. Speak to a fleet specialist when your trailer use changes, rather than waiting for renewal or a claim to expose a gap.