A fleet policy renewal should not be treated as a document to sign and file away. For a business with vans on call, lorries on delivery schedules or cars travelling between sites, the renewal is a practical opportunity to check that the policy still reflects how your operation actually works. A vehicle added without being declared, a change in driver profile or the wrong use class can create delays and uncertainty when you need to make a claim.
The price matters, but it is only one part of the decision. The right policy should support continuity: keeping the correct vehicles and drivers insured, providing suitable cover for the work they do, and making the policy straightforward to manage throughout the year.
Start your fleet policy renewal early
Begin reviewing your renewal around six to eight weeks before the policy end date where possible. Larger, specialist or mixed fleets may need longer, particularly if they include courier vans, HGVs, minibuses, agricultural vehicles, plant or hire-and-reward work.
Starting early gives you time to gather accurate information, deal with insurer questions and consider alternatives without a last-minute rush. It also gives your broker a clearer picture of the risks an insurer is being asked to cover. That can be especially useful after a year of growth, claims activity or operational change.
A renewal invitation is based on the information currently held. If that information is out of date, the premium and cover terms may not be suitable for the year ahead. Treat the invitation as a prompt to review, rather than proof that nothing has changed.
Build an accurate picture of your fleet
Insurers assess a fleet on more than the number of vehicles. They will want to understand what is being driven, who is driving it, where it goes and the work it carries out. Clear, up-to-date information helps avoid unnecessary back-and-forth and supports a more meaningful comparison.
Check vehicles, drivers and vehicle use
Review your vehicle schedule against the fleet you operate now. Include vehicles purchased, disposed of or temporarily off the road, as well as trailers, specialist bodies and plant where relevant. Registration details, values, security features and overnight locations should be correct.
Driver information deserves the same attention. Check ages, licence types, convictions, claims history and whether drivers have joined or left the business. A policy covering any driver may be useful for a changing workforce, but it can cost more than a restricted-driver arrangement. The best option depends on how often drivers change, how urgent journeys are and whether named-driver administration is manageable for your team.
Vehicle use is another common source of problems. Local deliveries, nationwide haulage, commuting between depots, carriage of tools, passenger transport and courier work are not interchangeable. A builder using a van to transport tools faces different exposures from a same-day delivery business working to tight schedules. Explain the day-to-day use plainly, including mileage, operating areas, overnight parking and any international travel.
Review cover, not just the renewal premium
A lower premium can be attractive, but it may be linked to a higher excess, narrower cover or conditions that are harder for your business to meet. Compare the overall policy rather than relying on a headline figure.
Third party only cover meets the legal minimum for road use, while third party, fire and theft adds protection for theft and fire. Comprehensive cover can include accidental damage to your own vehicles, subject to the policy terms. The appropriate level depends on vehicle values, finance arrangements, cash flow and your ability to repair or replace a vehicle following an incident.
Also check whether the policy includes, or can be extended to include, features that matter to your operation. These may include windscreen cover, replacement vehicles, legal expenses, breakdown assistance, personal belongings, tools in transit and European use. Limits, excesses and eligibility conditions can vary widely, so the detail matters.
If your work involves carrying goods for customers, transport of passengers or use for hire and reward, say so at renewal. Motor fleet insurance may need to sit alongside goods in transit, public liability or employers’ liability cover. Looking at these requirements together can reduce gaps between policies and make administration easier.
Use claims information to improve the next policy year
Claims history is a key part of any fleet renewal. Gather a clear record of incidents, including open claims, fault status, settlement amounts where known and the action taken afterwards. Do not assume a small incident is irrelevant. Insurers look at patterns as well as individual claims.
A rise in reversing incidents may point to a depot layout issue, poor visibility or a need for refresher training. Repeated windscreen claims may lead to a review of routes, following distances or vehicle storage. Theft losses could mean reviewing keys, alarms, tracking or overnight parking arrangements.
Showing that your business has identified a trend and introduced proportionate controls can be helpful. It does not guarantee a particular price or acceptance, but it gives a more complete account of the risk than claims figures alone. Keep evidence where practical, such as driver handbook updates, training records, telematics reports or maintenance procedures.
Prepare the information insurers are likely to request
A well-prepared renewal submission is easier to assess and less likely to be held up by missing details. For most fleets, have the following ready:
- an up-to-date vehicle list, including registrations, vehicle types, values and ownership status;
- a driver list or driver eligibility criteria, with relevant licence and claims information;
- a five-year claims record or no-claims evidence where available;
- a clear description of business activities, vehicle use, mileage and operating locations; and
- details of risk management measures, security, maintenance and any material changes expected in the coming year.
Be open about changes, even where they may appear unfavourable. Adding higher-value vehicles, expanding into a new region, taking on younger drivers or moving into courier work can affect the insurer’s view of the risk. Providing the information early is far better than discovering later that the policy was arranged on an incomplete basis.
Consider how the policy will work during the year
The right renewal arrangement is not only about what happens on the renewal date. Consider how easily vehicles and drivers can be added or removed, who in your business is authorised to make changes, and what documents need to be retained. One fleet policy with a single renewal date can simplify administration for businesses operating a mixture of cars, vans and specialist vehicles.
Payment options also deserve a practical review. Paying annually may suit some businesses, while monthly instalments can help spread the cost. Check the total payable, any finance arrangement and what flexibility is available if the fleet changes. The cheapest route is not always the most helpful if it creates pressure elsewhere in the business.
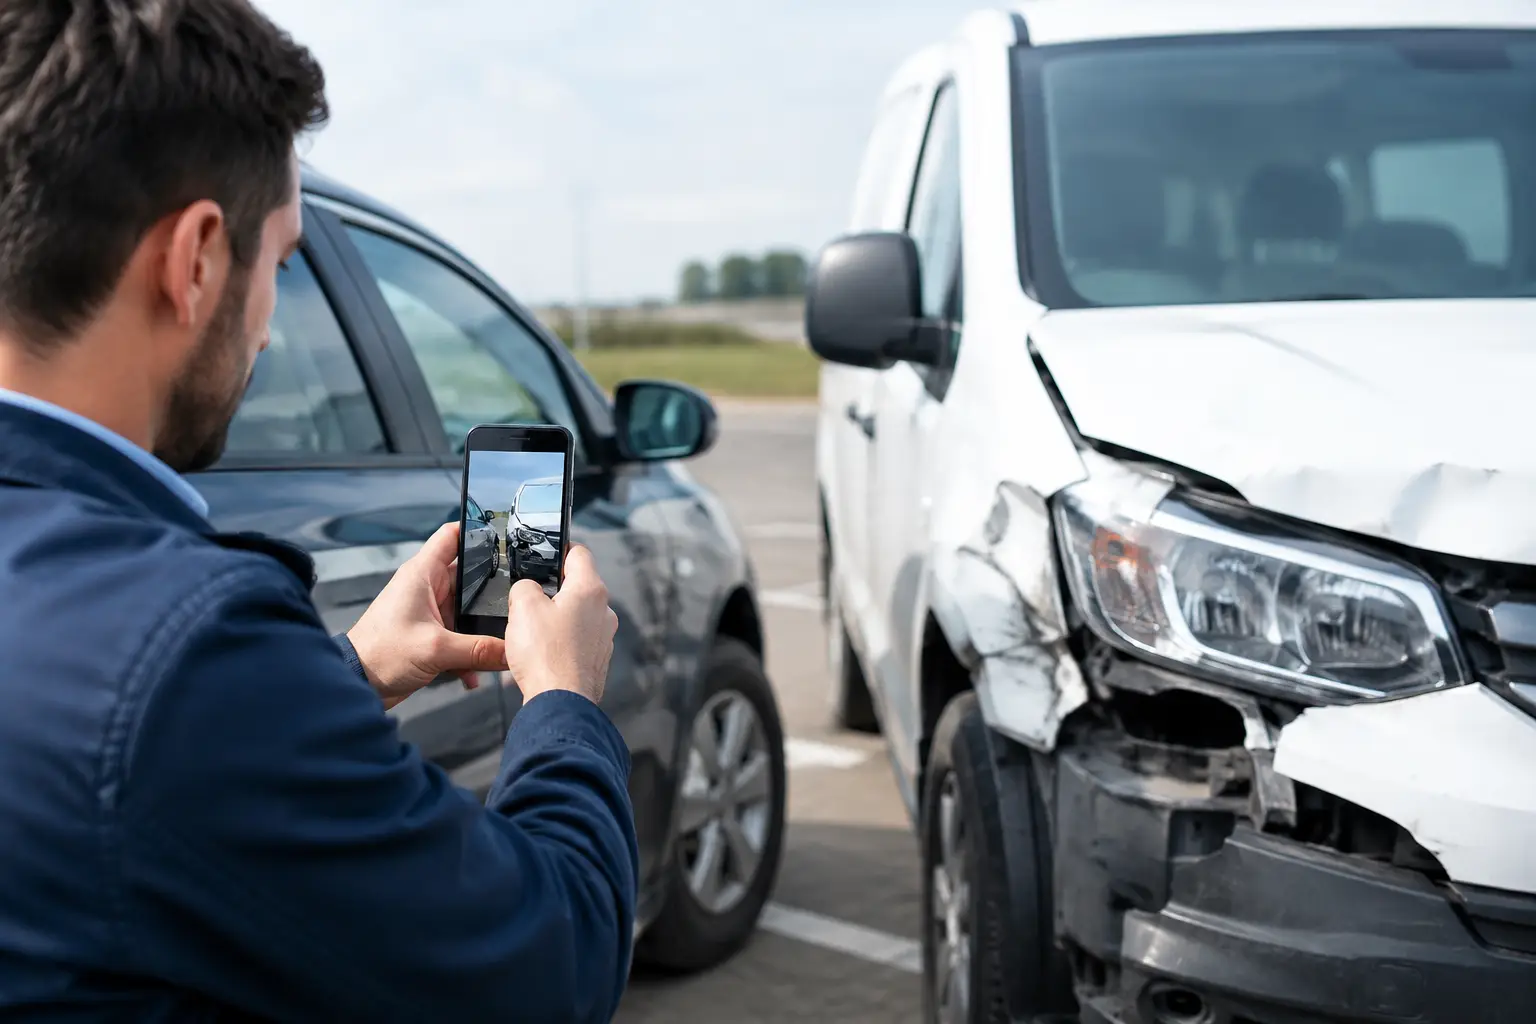
Claims support should be part of the decision too. Ask how incidents should be reported, what information drivers need to collect at the scene, and how repairs, replacement vehicles and third-party communications are handled. A simple internal accident-reporting process can save valuable time when a driver is dealing with an unexpected incident.
Avoid common renewal mistakes
The most avoidable mistake is renewing automatically without reviewing the schedule. Others include assuming occasional work is covered, leaving departed drivers on the policy, underestimating annual mileage or failing to declare a change in trade. These are not merely administrative details. They can affect whether cover applies and how a claim is handled.
It is also sensible to avoid comparing policies on excess alone. A lower excess may be useful, but the premium increase may not be worthwhile for a fleet that can comfortably absorb smaller losses. Conversely, a very high excess can create an unwelcome cost each time a vehicle is damaged. The right balance depends on your claims record, vehicle values and financial position.
An independent specialist can help present your operation clearly to suitable insurers and explain the terms in plain English. Fleet Brokers can review mixed and specialist fleets, helping businesses compare options while keeping the focus on suitable cover and day-to-day practicality.
Before you accept your next renewal, give the policy schedule, driver arrangements and vehicle use one final check. A short conversation now can help keep your vehicles properly insured and your business moving when the working day does not go to plan.